

Using FOVISSSTE to Buy Land or Build Your Home
Can you use your FOVISSSTE loan to buy a plot of land or build your house? Here's what to know.
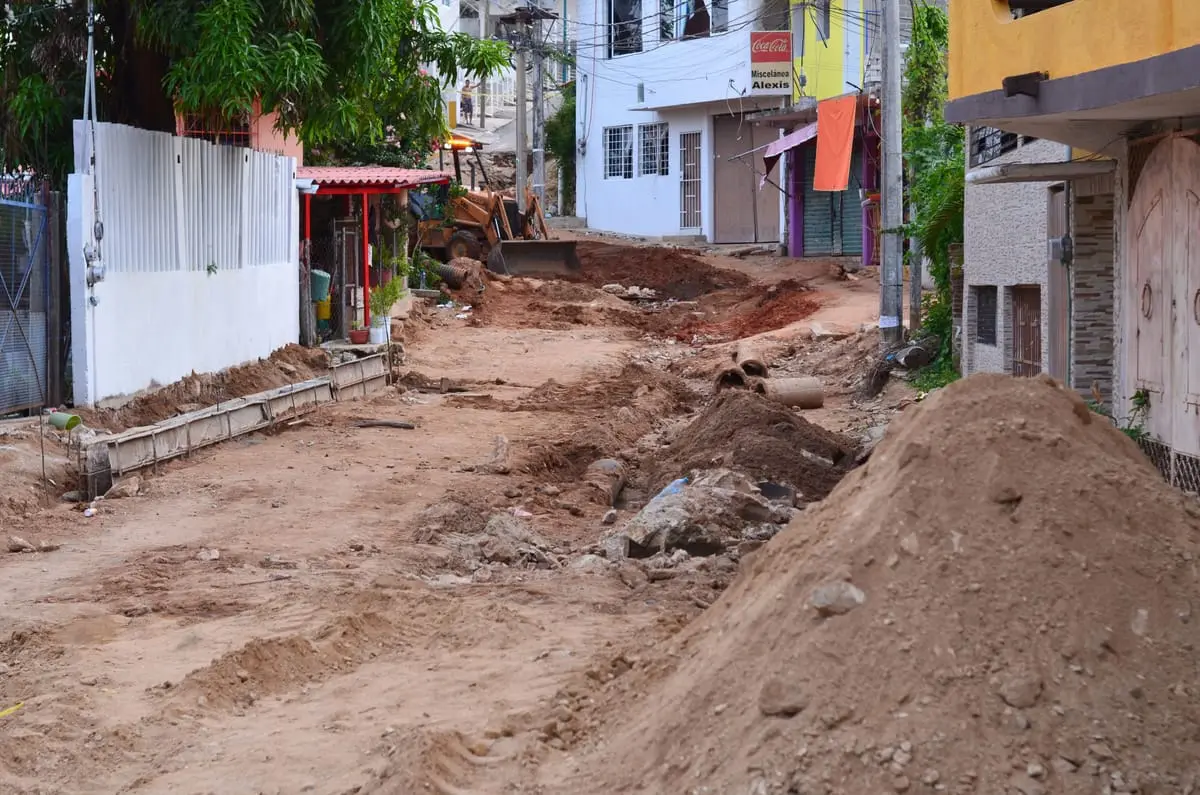
Most government workers think of their FOVISSSTE loan only as a way to buy a finished home, but the Institute also offers programs to build on land you already own and, under certain modalities, even to purchase the land and build on it. Conditions change often and not every product is available at all times, so in this 2026 guide we explain, in general terms and without figures that could quickly become outdated, which modalities typically exist, what requirements they ask for, how the appraisal (avalúo) affects the process, and how it differs from a bank construction loan.
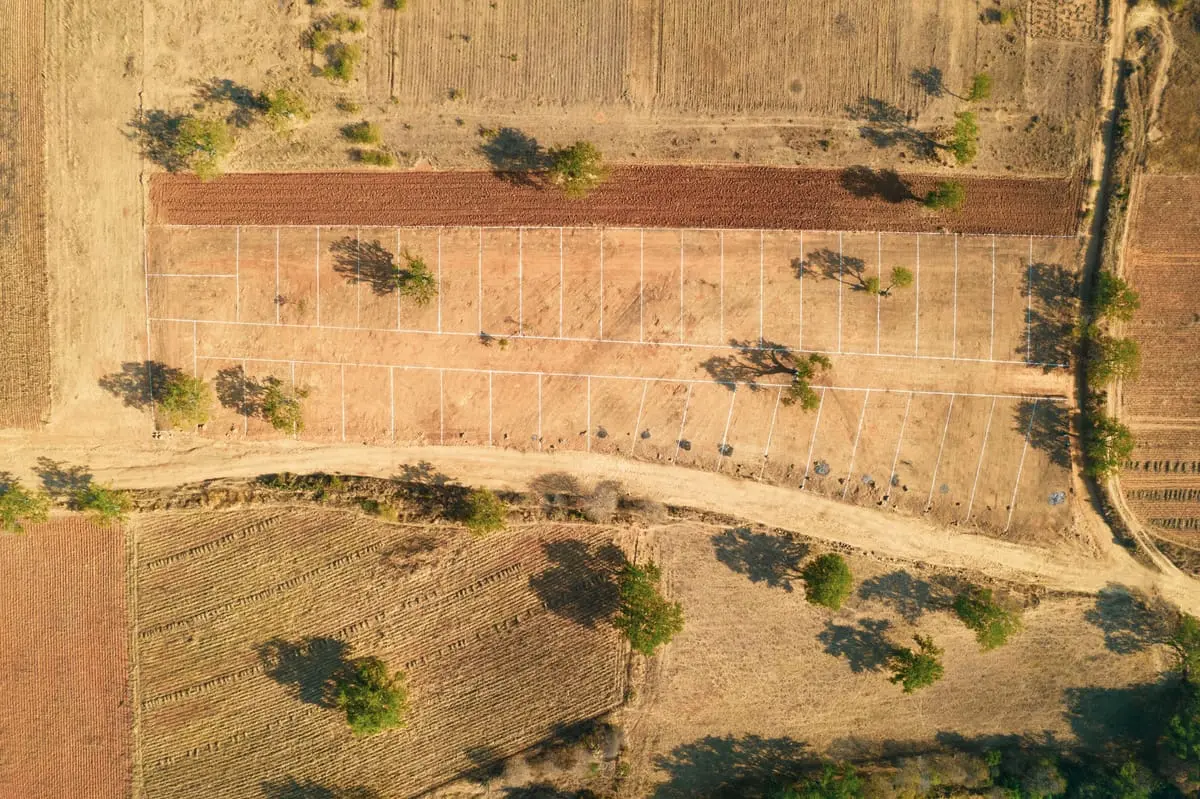
Can you use FOVISSSTE for land or construction?
The short answer: generally yes, but with important caveats. The ISSSTE Housing Fund (FOVISSSTE) has offered programs over the years aimed not only at buying new or used homes, but also at building on land you own and at improving or expanding an existing house. The availability of each product, its amounts and its rules change depending on the call for applications (convocatoria) and the year, so you should always confirm the current conditions directly with the Institute before making any decisions.
One key point is that FOVISSSTE tends to focus more on financing construction on land that is already yours than on buying a vacant lot on its own. Purchasing land alone, with no associated housing project, is not always an eligible purpose, and when it is, it is usually tied to subsequent construction.
Key fact
The loan is not the same thing as your savings. In addition to the amount the Fund grants you, you have the balance accumulated in your ISSSTE Housing Subaccount (Subcuenta de Vivienda), which can be added to the project. Check both amounts separately when planning your construction budget.
Modalities for building with FOVISSSTE
Although the commercial names of the products change over time, in practical terms the purposes related to land and construction usually fall into these groups:
Construction on your own land
This is the most common modality when you already own the lot. The financing goes toward building the home, and you are normally required to have the land deeded in your name (escriturado), free of liens, and zoned for residential use. The funds may be released as the work progresses or according to the scheme the Institute defines.
Land purchase plus construction
Some calls for applications have included programs that allow you to combine the purchase of the land with the construction of the house in a single project. It is not always an available product, and it usually requires the land to meet specific legal and technical conditions. If this route interests you, look at land for sale that comes with escrituras (property deeds) and utilities, as that makes the process much easier.
Expansion, repair or improvement
If you already own a home and want to expand or remodel it, the Fund has also offered lines for that purpose. The amounts tend to be smaller than a full construction loan, designed for partial work rather than building a house from scratch.
Before you commit
The names, amounts and conditions of each modality vary by call for applications. Don't assume that a product that existed a few years ago is still the same: check the current catalog on the official portal and, if possible, visit a service office before signing any down payment or construction contract.
General requirements
Since each modality has its own fine print, here we summarize the requirements that are most often requested. Treat them as a general guide, not a definitive list:
- Be a worker in the service of the State with a current employment relationship and contributing to the ISSSTE.
- Meet the points or seniority required by the scheme in the relevant call for applications.
- The land must be deeded in your name, free of liens and with no outstanding predial (property tax) debts.
- Have residential land use and, depending on the case, basic utilities available.
- Submit a construction project or budget when the purpose is to build.
- Not have an active FOVISSSTE loan that prevents you from starting a new one.
If you want to understand the general framework of the loan, its types and how it is granted, we recommend first reading our guide to FOVISSSTE requirements and how it works.
The role of the appraisal
Whether you are buying land or building, the appraisal (avalúo) is a central piece of the process. It is a report prepared by an authorized appraiser or valuation unit that determines the value of the property or the project. In a construction loan, in addition to the value of the land, the estimated value of the work is usually considered, based on the project and the budget submitted.
It is essential that the appraisal supports the amount you are requesting: if the appraised value comes in lower than you expected, the approved loan may not cover the full cost and you would have to contribute the difference. That is why it is important to work with realistic budgets. You can use our tool to calculate the value of a property and cross-check figures before committing.
| Item | Home purchase | Land + construction |
|---|---|---|
| What is appraised | The finished house | Land and construction project |
| Release of funds | In a single payment | Usually tied to construction progress |
| Construction documents | Not applicable | Project, budget and permits |
Restrictions to keep in mind
Using the loan for land or construction comes with additional conditions compared to buying a ready-made house. Here are some of the most common limitations to keep in mind:
Watch out for these points
- Buying land "outright," with no housing project, is not always an eligible purpose.
- The lot must be regularized: without clear escrituras, the loan is unlikely to be approved.
- Release of funds by construction progress requires meeting deadlines and inspections, which lengthens the process.
- The approved amount depends on the appraisal and the project, not just on what you want to spend.
- Construction cost overruns are your responsibility if the budget falls short.
Planning with a margin is key. Construction almost always costs more and takes longer than expected, so a cushion of your own funds will keep you from having to halt the work. To gauge the real cost, see our guide on how much it costs to build a house in 2026.
FOVISSSTE vs. a bank construction loan
A bank can also finance construction on land you own through its self-build mortgage loans (créditos hipotecarios de autoconstrucción). The choice between the two depends on your profile, your income and the conditions in effect. Broadly speaking, here is how they compare:
- Source of funds: FOVISSSTE comes from your housing fund as a government worker; the bank loan comes from the financial institution.
- Use of your savings: with FOVISSSTE you can add the balance of your Housing Subaccount; with a bank, that does not apply.
- Income requirements: banks usually ask for proof of income and a stricter credit history review.
- Flexibility of amounts: a bank loan may offer larger amounts depending on your ability to pay, often with different rates and fees.
- Compatibility: in certain cases there are schemes that let you combine both, but you should confirm current availability.
Compare before you decide
Always ask for the Total Annual Cost (CAT), the term and the breakdown of fees for each option. A small difference in the rate or in the charges can add up to a lot of money over the years of a construction loan.
Frequently asked questions
Can I use FOVISSSTE just to buy land?
Not always. Buying a standalone plot of land, with no associated housing project, is not an eligible purpose under every scheme. When it is allowed, it is usually tied to subsequent construction. Confirm the current modality with the Institute.
Does the land have to be in my name?
To build on your own land, the lot is typically required to be deeded in your name, free of liens and zoned for residential use. Without a clear legal status, the process is unlikely to move forward.
How is the money for construction delivered?
It depends on the scheme. In construction loans it is common for the funds to be released in stages as the work progresses, with inspections along the way, rather than being delivered all at once.
Is FOVISSSTE or a bank loan better for building?
There is no single answer. FOVISSSTE makes use of your housing savings and usually has conditions designed for government workers; a bank may offer larger amounts depending on your ability to pay. Compare the CAT, term and requirements before choosing.
Ready for your construction project?
Find the ideal land or property for your loan and estimate its value before taking the next step.
Listings
Recent properties
 For sale
MX$1,440,000
Land
Land for Sale in Residencial Lomas del Dorado
Boca del Río, Veracruz
 For sale
MX$3,900,000
House
House for Sale in Las Lomas, Riviera Veracruzana | 3 Bedrooms with Private Bathrooms
Alvarado, Veracruz
 For sale
MX$10,900,000
Land
Attention Investors
Puerto Vallarta, Jalisco
Keep reading
Related articles

Buying Land to Build vs. a Finished Home in Mexico
Build or buy a house? Compare costs, timelines, risks and paperwork between buying a lot to build on and buying a finished home in Mexico.
Carlos Mendoza

Build vs. Buy a Home in Mexico: What Pays Off in 2026
Build or buy a home? We compare costs, timelines, risks and financing to help you decide which option makes more sense for you.
Carlos Mendoza

Home Loans for Teachers in Mexico: Fovissste and Other Options
Mortgage options for teachers buying a home in Mexico: Fovissste, Infonavit, bank loans and programs for public and private school educators.
María Elena Rodríguez
Monterrey's Water Crisis: What It Means for Homebuyers
Monterrey's water crisis: what happened in 2022, how the dams stand today, what infrastructure was built, and what to check in a home before buying in the metro area.
Inmobiliaria32 Team
Credit and mortgages
Keep learning before you decide
85 guides on credit and mortgages, and thousands of properties listed across Mexico.